
Loading page
Loading card
Standard Chartered Bank
5% back on fuel, phone bills and utility bills — the three things everybody pays every month
One-time
Waived on ₹90,000/yr
Capped at ₹200/month
Score 700+
Applying takes you to Standard Chartered Bank. CredSpy does not process applications, and the ranking on this site is never influenced by commission.
Best for
Terms structured from published copy
3 reward rates with their caps, taken from Standard Chartered Bank’s own published wording rather than checked against its terms document. Verify before you rely on a figure.
Terms effective from 9 Oct 2026.
See where each figure came fromFuel
Pays up to ₹200 a month — reached at about ₹4,000 of spend
Bills
Pays up to ₹200 a month — reached at about ₹4,000 of spend
Utilities
Pays up to ₹100 a month — reached at about ₹2,000 of spend
These rates share one ceiling: ₹200 a month across the card, not per category.
Only fuel, phone bills and utility bills earn cashback. Everything else earns reward points instead. All exclusions
Data-driven verdict based on net earnings after fees and caps.
Key strength
5% on Fuel — Maximum Rs. 100 per transaction. Rs. 500 a month across fuel, phone and utility bills combined., up to ₹200 per month.
Biggest limitation
Cashback stops at Rs. 200 a month on fuel, Rs. 200 on phone bills and Rs. 100 on utilities — Rs. 500 a month in total, and Rs. 100 on any single transaction.
Priced with caps, exclusions, and annual fee deducted live.
Monthly spending — ₹54,000
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Import a statement and this runs on your real spending instead of the sliders.
Click any drawer below to inspect fee schedules, lounge terms, reward multipliers, and exclusions.
Everything else the issuer publishes about this card. All of it is on this page and searchable — open only what you need.
5%
cappedFuel
Pays up to ₹200 per month — reached at about ₹4,000 of spend.
Maximum Rs. 100 per transaction. Rs. 500 a month across fuel, phone and utility bills combined.
5%
cappedBills
Pays up to ₹200 per month — reached at about ₹4,000 of spend.
Telephone bills above Rs. 750, maximum Rs. 100 per transaction.
5%
cappedUtilities
Pays up to ₹100 per month — reached at about ₹2,000 of spend.
Utility bills above Rs. 750, maximum Rs. 100 per transaction.
| Charge | Amount | Condition |
|---|---|---|
| Joining fee | ₹885 | — |
| Annual / renewal fee | ₹885 | Rs. 750 in the first year and Rs. 750 on renewal, reversed on spends of Rs. 90,000 or more in the preceding year |
| Add-on card | The issuer publishes no separate add-on card fee for this card. | — |
| Cash withdrawal | 3%, min ₹300 | 3% of the amount withdrawn, subject to a minimum of Rs. 300 |
| Late payment | Tiered by balance: nil up to Rs. 100, Rs. 100 on Rs. 101–500, Rs. 500 on Rs. 501–5,000, Rs. 700 on Rs. 5,001–10,000 and Rs. 1,200 above Rs. 10,000, plus Rs. 100 if the minimum due is unpaid for two consecutive months | — |
| Foreign currency markup | 3.5% | — |
Interest only applies if a balance is carried past the due date. Paying in full each month costs nothing, and no reward rate on this card comes close to offsetting the interest if you do not.
Fees exclude GST unless stated. Charges can change — confirm against the issuer's current schedule before applying.
Year one
Rewards only
no welcome value is recorded
Every year after
₹90,000 a year
is what it takes to keep the ₹885 fee off — about ₹7,500 a month
This card carries no airport lounge access.
No fuel surcharge waiver is published for this card.
Only RuPay credit cards can be linked to UPI, so this card cannot be used to pay by UPI.
Welcome — once
None
no welcome benefit is recorded for this card
Milestones — every year
2
spend thresholds you can reach again each year
No welcome benefit is recorded.
Spend ₹1 a month
5% cashback on telephone bills above Rs. 750, up to Rs. 200 a month
Spend ₹1 a month
5% cashback on utility bills above Rs. 750, up to Rs. 100 a month
Scored against these published criteria only. No bureau pull, and no approval guarantee — the issuer decides.
CredSpy never collects these. You submit them to the issuer during their own application.
No reviews yet
CredSpy publishes only reviews left by real cardholders. Nothing here is generated, bought or seeded — so this stays empty until someone who holds the card writes one.
 Standard Chartered BankStandard Chartered Smart Credit Card₹499
 Standard Chartered BankStandard Chartered Rewards Credit Card₹1,180
 Suryoday Small Finance BankSuryoday SFB FD-Backed Credit Card₹177
 IDFC BANKIDFC FIRST Mayura Credit Card₹7,079
 Indian Overseas BankIndian Overseas Bank ZET FD Credit CardLifetime free
 RBL BankRBL Bank SalarySe UP Credit Card₹589
| Card | Annual fee | Headline rate | Lounge |
|---|---|---|---|
| Standard Chartered Super Value Titanium Credit Card · this card | ₹885 | 5% fuel | No |
| Standard Chartered Smart Credit Card | ₹499 | Up to 2% cashback | No |
| Standard Chartered Rewards Credit Card | ₹1,180 | Up to 4 reward points per ₹150 | Included |
| Suryoday SFB FD-Backed Credit Card | ₹177 | See card | No |
| IDFC FIRST Mayura Credit Card | ₹7,079 | Up to 10 reward points per ₹150 | Included |
Headline rates are not comparable on their own — each card caps and excludes differently. Run your own spending through the switch calculator to see which of these actually pays you more.
₹885 plus GST, waived on ₹90,000 of annual spend.
The strongest published rate is 5% on fuel, capped at ₹200 per month — so roughly ₹4,000 of spend reaches the maximum on that tier. The calculator above prices your own basket with every cap and exclusion applied.
No — airport lounge access is not offered on this card.
Only RuPay credit cards can be linked to UPI, so this card cannot be used to pay by UPI.
Only fuel, phone bills and utility bills earn cashback. Everything else earns reward points instead. Only fuel, phone bills and utility bills earn cashback. Everything else earns reward points instead. Only fuel, phone bills and utility bills earn cashback. Everything else earns reward points instead.
Standard Chartered Bank publishes about ₹55,000 a month for salaried applicants, and it is usually issued above a 700 credit score. Meeting the criteria is not an approval — the issuer decides.
Redeemed through the issuer's rewards programme as published on the card's product page
You can apply online through our website by filling out the application form and uploading the required documents. You may also visit your nearest branch for in-person assistance.
Yes, you can request a limit increase through internet banking, mobile app, or by contacting customer care. Approval depends on your credit history and income. If you want, I can also create a more engaging, SEO-friendly FAQ section for your credit card website that boosts trust and conversions. Would you like me to prepare that next?
A late payment fee and interest will be charged. Missing payments can also impact your credit score.
5% on fuel at all fuel stations up to Rs. 200 a month, 5% on telephone bills above Rs. 750 up to Rs. 200 a month, and 5% on utility bills above Rs. 750 up to Rs. 100 a month. Every single transaction is capped at Rs. 100 of cashback. Other spending earns reward points.
Rs. 750 in the first year and Rs. 750 on renewal. Standard Chartered reverses the renewal fee for cardholders who spend Rs. 90,000 or more in the preceding year — about Rs. 7,500 a month.
Rs. 500 a month at most, across all three categories, which is Rs. 6,000 a year. Against a Rs. 750 fee that is reversed above Rs. 90,000 of spend, the card is comfortably positive for anybody whose fuel and bills reach the caps.
You must be between 21 and 65 years old with a minimum monthly income of Rs. 55,000. Standard Chartered does not publish a credit score requirement for this card.
No lounge access is published for this card. It is built around recurring bills rather than travel.
Yes, for two of the three categories. Telephone and utility bill transactions must be above Rs. 750 to earn cashback. Fuel has no published minimum, but the Rs. 100 per-transaction cap means the 5% stops at Rs. 2,000 of fuel in one fill.
Credit card fees, rewards and benefits change. Please verify the latest terms on the issuer's website before applying. CredSpy earns a commission on some applications; it never affects rankings or what is written here.
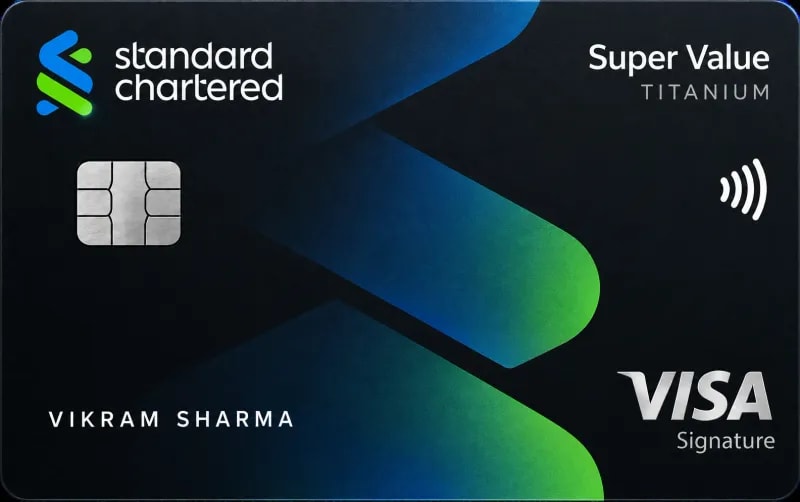
Standard Chartered Super Value Titanium Credit Card — 5% on fuel, up to ₹200 per month. ₹885 a year.